Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4918
Press 'Enter' after typing page number.
661 to 680 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
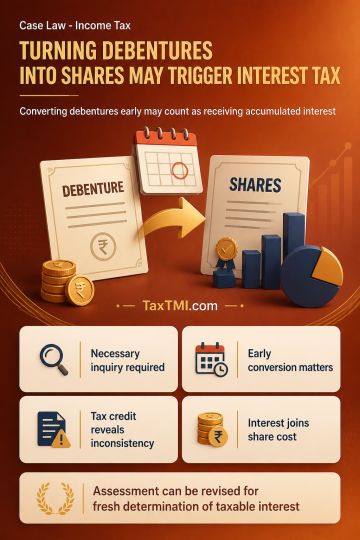
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918