Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
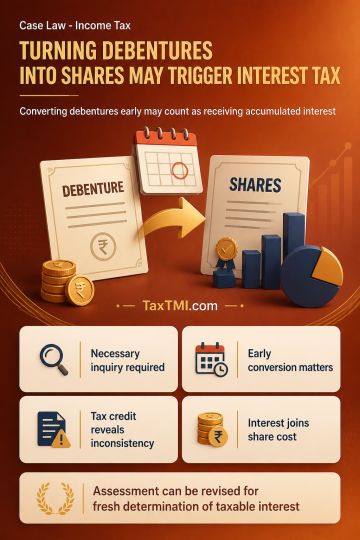
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915