Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
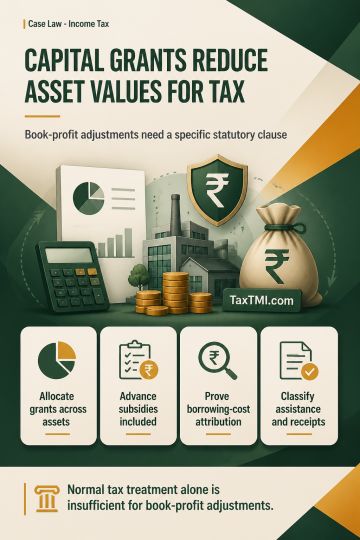
Capital grants, subsidies and consumer contributions reduce the actual cost or written-down value of relevant assets for depreciation. Where not directly attributable to a particular asset, they require allocation among the affected assets at their respective depreciation rates. Book-profit adjustments for such grants, including subsidy grants received in advance, require an identified clause in the Explanation to section 115JB(2); treatment under normal tax provisions alone is insufficient. Borrowing-cost capitalisation depends on direct attribution to qualifying capital projects and cannot rest on an unsupported assumed historical rate or unsubstantiated accounting-method change. Assistance for beneficiary-owned solar systems is revenue in nature, while business-linked staff-loan interest and miscellaneous receipts are business income; residual rental and staff recoveries may be income from other sources.
Capital grants, subsidies and consumer contributions reduce the actual cost or written-down value of relevant assets for depreciation. Where not directly attributable to a particular asset, they require allocation among the affected assets at their respective depreciation rates. Book-profit adjustments for such grants, including subsidy grants received in advance, require an identified clause in the Explanation to section 115JB(2); treatment under normal tax provisions alone is insufficient. Borrowing-cost capitalisation depends on direct attribution to qualifying capital projects and cannot rest on an unsupported assumed historical rate or unsubstantiated accounting-method change. Assistance for beneficiary-owned solar systems is revenue in nature, while business-linked staff-loan interest and miscellaneous receipts are business income; residual rental and staff recoveries may be income from other sources.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918