Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
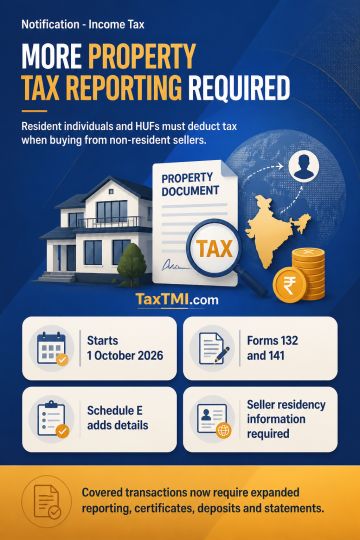
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915