TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
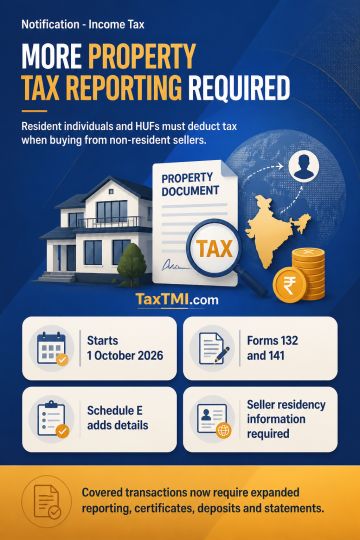
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918