Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    TDS on compulsory acquisition compensation is impermissible, requiring release of amounts withheld from land-losers' compensation.
    Transfer pricing boundaries require genuine separate services, aggregated linked placements, and proper profit-split analysis for branch dealings.
    Exempt-income disallowance excludes concessional taxable income, mutual receipts, and investments funded by sufficient interest-free own funds.
    Block-of-assets depreciation prevents individual asset valuation on sale where the commercial block continues and its WDV exceeds consideration.
    Benami transaction requirements cover cash routed through benamidars, while review fails without an apparent record error.
    Cattle-feed imports: Test reports showing unfitness for human consumption require release pending adjudication despite speculative diversion concerns.
    Reasonable-period limits on duty drawback recovery invalidate delayed action where no fraud or suppression is alleged.
    Transit import prohibitions apply to Pakistan-origin goods bound for Nepal, while conflicting origin evidence requires statutory determination.
    Release of detained cargo containers requires payment of de-stuffing charges and notice to the importer before administrative orders.
    Customs valuation evidence for used machinery requires reliable corroboration; defective procedure defeats demands, confiscation, fines, and penalties...
    Civil court jurisdiction over company-held property supports partition suits where plaint averments require trial on ownership and HUF funding.
    CIRP restoration discretion requires judicial reasons, fair process and comparative value assessment before rejecting a unanimous creditor decision.
    Statutory Tax Charges Cannot Create Secured-Creditor Status When IBC Security Interest Requires Consensual Security Arrangements
    Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
    PMLA bank-account freezing permits sealed reasons, while proceeds-of-crime disputes proceed through statutory adjudication and appeal.
    Provisional attachment for diverted Tramadol exports was sustained, with property valued at fair market value on acquisition.
    Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
    Refund claims against unmodified self-assessments fail, while post-clearance credit notes do not overcome unjust enrichment.
    Winding-up safeguards require inspection-report disclosure, a hearing and recorded reasons before a co-operative society may be liquidated.
    Limitation for Revenue refund appeals begins when the order is issued, barring delayed departmental challenges beyond condonable time.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Effective 1 October 2026, the TDS compliance framework extends...

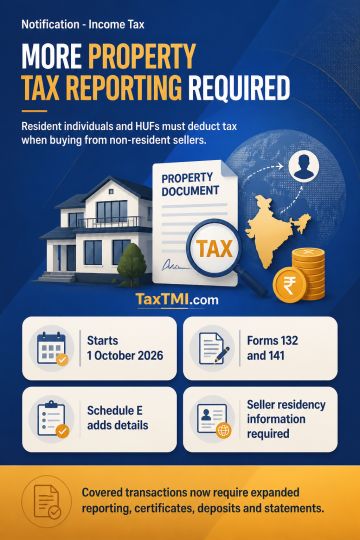
TDS reporting for property transfers now covers resident individual and HUF buyers acquiring property from non-resident sellers.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 23, 2026 Notifications
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.

Topics

Acts Income Tax