Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Statutory pre-deposit enables tax appeals on merits, with prior deposits adjusted and balance demand stayed after compliance.
    Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
    Recruitment eligibility rules expand acceptable qualifications, define grade conversions, and remove the desirable experience requirement for legal-st...
    Portfolio manager registration and client protection impose fiduciary, disclosure, asset-segregation and compliance duties under the new framework.
    Specified-person certification expands to NISM courses, updates market-participant terminology, and permits extended certificate validity and renewal ...
    Bullion vaulting framework expands to ETFs and derivatives, imposing registration, segregation, reconciliation, compliance reporting, and indemnity ob...
    INR derivative controls prohibit rebooking and reduce unverified hedging limits while retaining maturity rollovers for users.
    Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
    Temporary supplementary SCMTR filings for console cargo permit missing cargo details without restoring general import filing access.
    Manifest amendment rules require deletion and refiling for fundamental Bill of Lading changes, while streamlining CSN validation and cancellation.
    GST demand summary discrepancies may qualify as rectifiable clerical errors despite ordinary rectification limitation periods.
    Retrospective input tax credit relief covers specified delayed returns filed before the statutory cut-off date and requires reconsideration.
    Natural justice requires hearing a director separately before confirming personal penalty in the company's appeal.
    Transitional cash refunds for reverse-charge service tax remain governed by existing law under GST transition provisions.
    Credit-note tax reporting errors do not create wrongful input tax credit where no revenue loss or duplicate reduction occurs.
    Statutory appellate jurisdiction excludes direct challenges to original adjudication orders while the first appeal remains pending.
    Cancelled E-Way Bill verification requires portal-based transaction matching before determining whether tax liability arises from goods movement.
    Unaccounted stock found during survey requires assessment as supplied goods, not direct confiscation or a confiscation fine.
    Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
    Provisional input tax credit requires supplier tax payment; invoice-level matching governs interest, while unnotified interest grounds cannot stand.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Effective 1 October 2026, the TDS compliance framework extends...

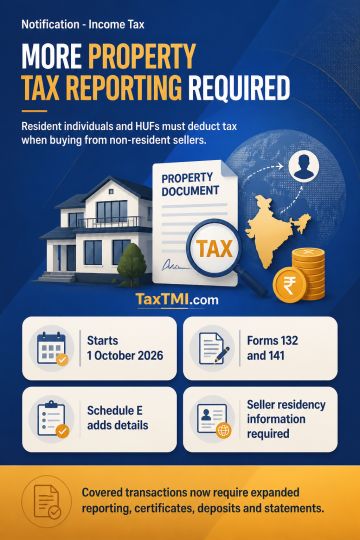
TDS reporting for property transfers now covers resident individual and HUF buyers acquiring property from non-resident sellers.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 23, 2026 Notifications
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.

Topics

Acts Income Tax