Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
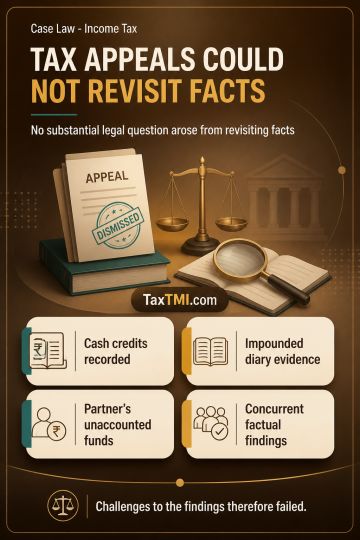
Concurrent factual findings on cash credits recorded in an impounded diary did not give rise to a substantial question of law in the income-tax appeals. The credits recorded in a partner's name were treated as unaccounted funds introduced by the partner into the partnership firm after considering the stated unaccounted sources. A plea to assess the entire diary amount in the partner's hands required reconsideration of those factual findings rather than resolution of a legal issue. The challenges therefore failed for want of a substantial question of law.
Concurrent factual findings on cash credits recorded in an impounded diary did not give rise to a substantial question of law in the income-tax appeals. The credits recorded in a partner's name were treated as unaccounted funds introduced by the partner into the partnership firm after considering the stated unaccounted sources. A plea to assess the entire diary amount in the partner's hands required reconsideration of those factual findings rather than resolution of a legal issue. The challenges therefore failed for want of a substantial question of law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916