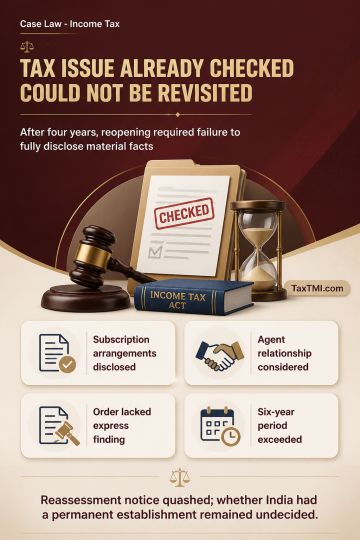
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915