Chartered engineer empanelment for customs valuation is temporarily suspended over competence, documentation and cargo examination safeguards violatio...
Transfer pricing comparability involves functional profiles and related party filters, while service advances require factual working capital assessme...
Transfer pricing comparables for software services depend on functional similarity and turnover-related factors affecting comparability and profitabil...
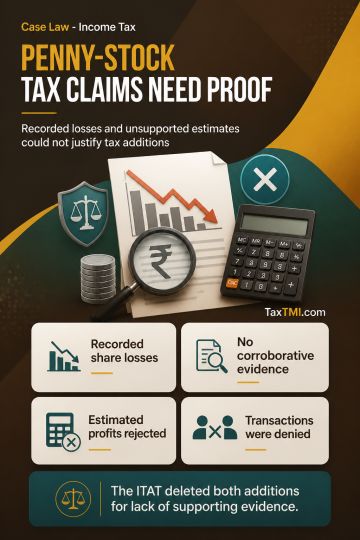
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates