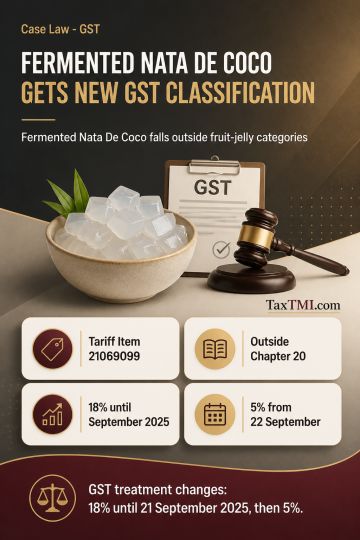
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Undisclosed-income additions for penny-stock transactions cannot rest solely on Investigation Wing information where recorded share purchases and sales show a loss and no substantive or corroborative evidence establishes unaccounted income. The ITAT therefore deleted that addition. It also deleted an estimated-profit addition for alleged share dealings: the taxpayer denied the transactions, and estimating profit from alleged turnover without substantive supporting material amounted to assumption, presumption and speculation. Both additions failed for lack of substantive and corroborative evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913