Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Stakeholder-list modification permits liquidators to update entries on new information, subject to notifying the Adjudicating Authority within prescri...
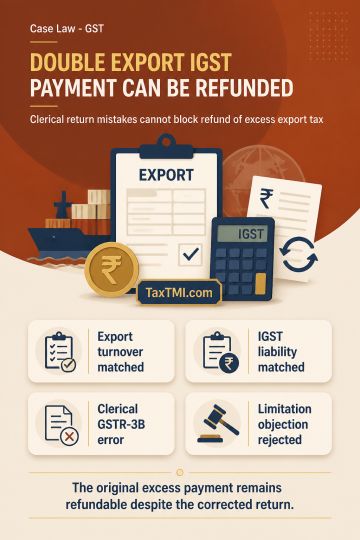
Excess IGST paid twice on export supplies is refundable where export turnover and IGST liability were correctly reported in GSTR-1 but mistakenly classified under supplies other than zero-rated supplies in GSTR-3B. The mismatch prevented automated customs refund, leading to a second IGST payment through a corrected return; refund of that second payment did not extinguish the claim for the original excess payment. A clerical reporting error, supported by return reconciliation, does not constitute a substantive breach justifying denial. Retaining tax paid twice would lack authority of law, and refund cannot be denied on procedural grounds or the stated limitation objection.
Excess IGST paid twice on export supplies is refundable where export turnover and IGST liability were correctly reported in GSTR-1 but mistakenly classified under supplies other than zero-rated supplies in GSTR-3B. The mismatch prevented automated customs refund, leading to a second IGST payment through a corrected return; refund of that second payment did not extinguish the claim for the original excess payment. A clerical reporting error, supported by return reconciliation, does not constitute a substantive breach justifying denial. Retaining tax paid twice would lack authority of law, and refund cannot be denied on procedural grounds or the stated limitation objection.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915