Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
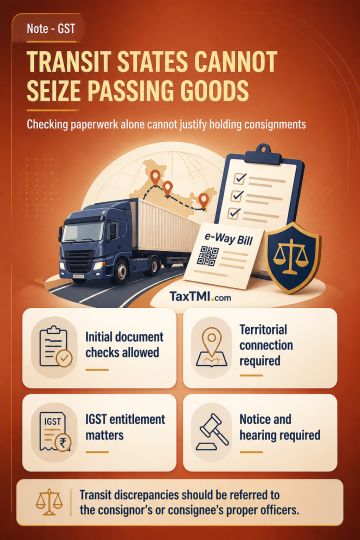
State GST officers may conduct initial document verification of inter-State consignments but cannot detain, seize or confiscate goods merely passing through their State. Cross-empowerment under CGST and IGST laws requires both administrative allocation of the taxpayer to the State and assignment of the relevant proper-officer function; it is not unrestricted authority. Coercive action under Sections 129 and 130 additionally requires territorial and fiscal nexus, including the State's entitlement to IGST apportionment under Section 17. For consignments originating and destined outside the intercepting State, discrepancies should be referred to the consignor's or consignee's proper officers. Confiscation requires statutory grounds, material supporting intent to evade tax where applicable, and notice and hearing; transit checks cannot become valuation assessments.
State GST officers may conduct initial document verification of inter-State consignments but cannot detain, seize or confiscate goods merely passing through their State. Cross-empowerment under CGST and IGST laws requires both administrative allocation of the taxpayer to the State and assignment of the relevant proper-officer function; it is not unrestricted authority. Coercive action under Sections 129 and 130 additionally requires territorial and fiscal nexus, including the State's entitlement to IGST apportionment under Section 17. For consignments originating and destined outside the intercepting State, discrepancies should be referred to the consignor's or consignee's proper officers. Confiscation requires statutory grounds, material supporting intent to evade tax where applicable, and notice and hearing; transit checks cannot become valuation assessments.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921