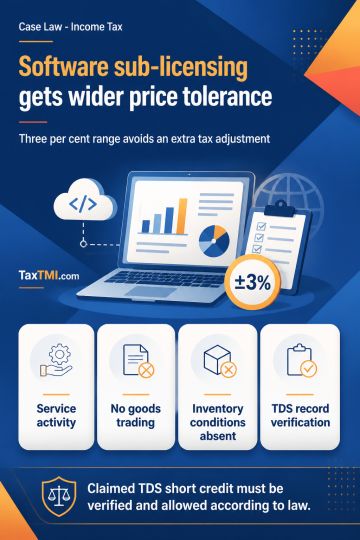
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
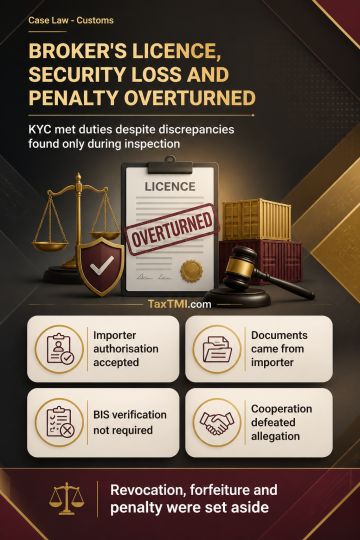
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Section 129(3)'s seven-day deadline for issuing notice after detention of goods and conveyance under GST is mandatory. The timeline limits coercive detention and seizure powers, protects against arbitrary or prolonged detention, and requires strict compliance because the provision uses "shall" and affects taxpayer rights. A delay of even one day in issuing the notice vitiates the resulting detention and penalty proceedings. Penalty orders issued or affirmed despite breach of this timeline are liable to be set aside, without preventing other proceedings permissible under the Act. Deposited penalty may be released following due verification.
Section 129(3)'s seven-day deadline for issuing notice after detention of goods and conveyance under GST is mandatory. The timeline limits coercive detention and seizure powers, protects against arbitrary or prolonged detention, and requires strict compliance because the provision uses "shall" and affects taxpayer rights. A delay of even one day in issuing the notice vitiates the resulting detention and penalty proceedings. Penalty orders issued or affirmed despite breach of this timeline are liable to be set aside, without preventing other proceedings permissible under the Act. Deposited penalty may be released following due verification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913