Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
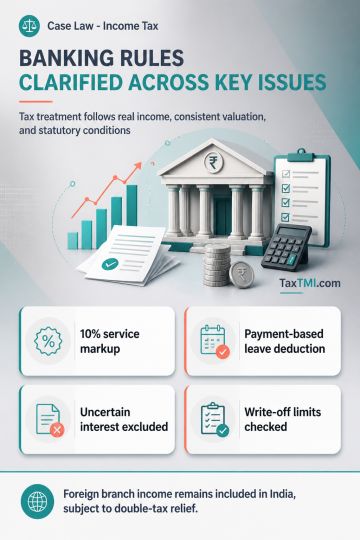
Intra-group technical and IT services are priced using a 10% cost mark-up, after crediting recoveries, because Safe Harbour margins did not apply for the relevant year. Actuarially measured pension and other employee-benefit liabilities arising from past service are accrued liabilities, while privilege-leave encashment remains deductible only on actual payment. Exempt-income expenditure requires limited recomputation excluding interest, considering only income-yielding investments, and capped at exempt income. Banking securities may be valued under a consistently followed recognised method reflecting real income; interest on non-performing advances or investments is not taxed where recovery is uncertain under prudential norms. Bad-debt provisions, recovery taxation, and deductions for non-rural write-offs require statutory-limit, prior-deduction, and factual verification. Foreign branch income remains included in Indian total income, subject to double-tax relief.
Intra-group technical and IT services are priced using a 10% cost mark-up, after crediting recoveries, because Safe Harbour margins did not apply for the relevant year. Actuarially measured pension and other employee-benefit liabilities arising from past service are accrued liabilities, while privilege-leave encashment remains deductible only on actual payment. Exempt-income expenditure requires limited recomputation excluding interest, considering only income-yielding investments, and capped at exempt income. Banking securities may be valued under a consistently followed recognised method reflecting real income; interest on non-performing advances or investments is not taxed where recovery is uncertain under prudential norms. Bad-debt provisions, recovery taxation, and deductions for non-rural write-offs require statutory-limit, prior-deduction, and factual verification. Foreign branch income remains included in Indian total income, subject to double-tax relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921