Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
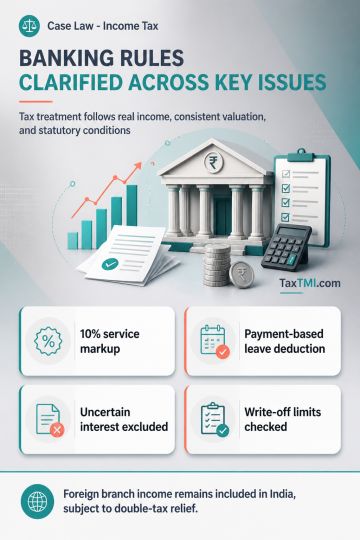
Intra-group technical and IT services are priced using a 10% cost mark-up, after crediting recoveries, because Safe Harbour margins did not apply for the relevant year. Actuarially measured pension and other employee-benefit liabilities arising from past service are accrued liabilities, while privilege-leave encashment remains deductible only on actual payment. Exempt-income expenditure requires limited recomputation excluding interest, considering only income-yielding investments, and capped at exempt income. Banking securities may be valued under a consistently followed recognised method reflecting real income; interest on non-performing advances or investments is not taxed where recovery is uncertain under prudential norms. Bad-debt provisions, recovery taxation, and deductions for non-rural write-offs require statutory-limit, prior-deduction, and factual verification. Foreign branch income remains included in Indian total income, subject to double-tax relief.
Intra-group technical and IT services are priced using a 10% cost mark-up, after crediting recoveries, because Safe Harbour margins did not apply for the relevant year. Actuarially measured pension and other employee-benefit liabilities arising from past service are accrued liabilities, while privilege-leave encashment remains deductible only on actual payment. Exempt-income expenditure requires limited recomputation excluding interest, considering only income-yielding investments, and capped at exempt income. Banking securities may be valued under a consistently followed recognised method reflecting real income; interest on non-performing advances or investments is not taxed where recovery is uncertain under prudential norms. Bad-debt provisions, recovery taxation, and deductions for non-rural write-offs require statutory-limit, prior-deduction, and factual verification. Foreign branch income remains included in Indian total income, subject to double-tax relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI