Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Page of 4913
Press 'Enter' after typing page number.
1281 to 1300 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Strict interpretation of the customs exemption required Disc...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Entry.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
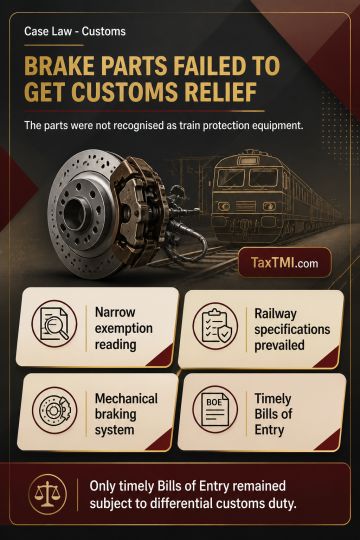
Strict interpretation of the customs exemption required Disc Brake Units and Pole Wheels to fall clearly within the recognised railway-engineering meaning of a Train Protection and Warning System (TPWS). As components of a mechanical or pneumatic axle-mounted braking system, rather than signal-based TPWS equipment, they did not qualify for concessional duty. Official railway specifications prevailed over contrary technical opinions. Differential customs duty could be demanded only for Bills of Entry within the normal limitation period invoked under section 28(1); extending the demand beyond that period under section 28(4) exceeded the show cause notice. The exemption claim failed, while the demand was restricted accordingly.
Strict interpretation of the customs exemption required Disc Brake Units and Pole Wheels to fall clearly within the recognised railway-engineering meaning of a Train Protection and Warning System (TPWS). As components of a mechanical or pneumatic axle-mounted braking system, rather than signal-based TPWS equipment, they did not qualify for concessional duty. Official railway specifications prevailed over contrary technical opinions. Differential customs duty could be demanded only for Bills of Entry within the normal limitation period invoked under section 28(1); extending the demand beyond that period under section 28(4) exceeded the show cause notice. The exemption claim failed, while the demand was restricted accordingly.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913