Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
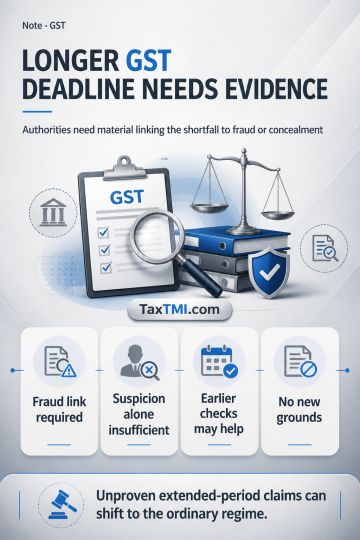
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915