Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Page of 4915
Press 'Enter' after typing page number.
1241 to 1260 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
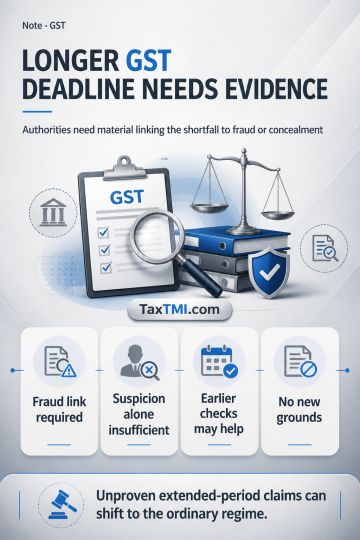
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915