Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
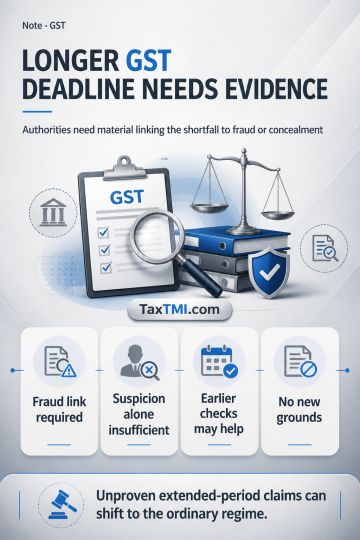
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI