Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Page of 4925
Press 'Enter' after typing page number.
1221 to 1240 of 98494 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
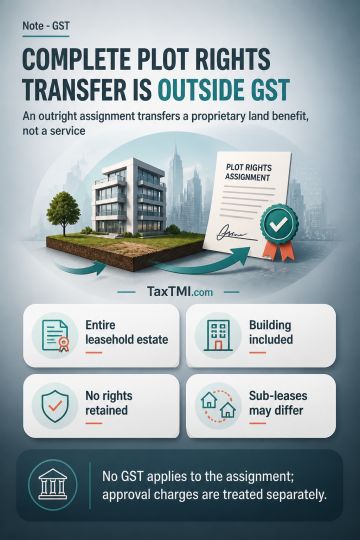
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925