Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
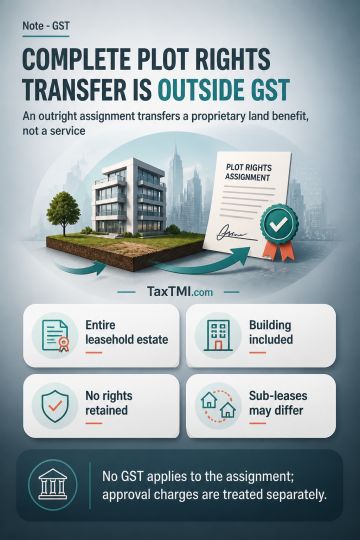
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915