Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Page of 4915
Press 'Enter' after typing page number.
1241 to 1260 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
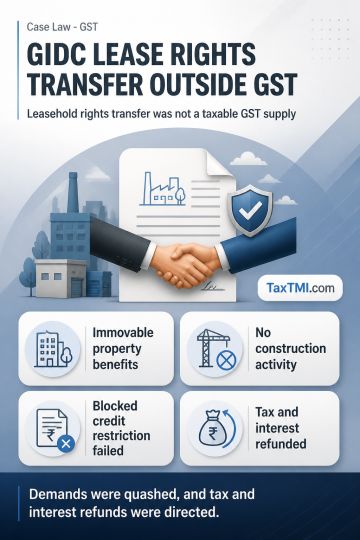
Assignment or transfer of leasehold rights in a GIDC industrial plot is characterised as a transfer of benefits arising from immovable property, not a taxable GST supply. GST charged on that transfer therefore lacks legal basis, and input tax credit reversal and interest premised on the assumed levy cannot stand. The blocked-credit restriction for goods or services used in construction of immovable property does not apply where no construction activity occurred. As the underlying transaction is not taxable and the blocked-credit premise fails, allegations of wrongful credit, fraud, wilful misstatement or suppression for section 74 proceedings, including consequential penalty, cannot be sustained. The adjudication and appellate demands were quashed, with refund of tax and interest directed.
Assignment or transfer of leasehold rights in a GIDC industrial plot is characterised as a transfer of benefits arising from immovable property, not a taxable GST supply. GST charged on that transfer therefore lacks legal basis, and input tax credit reversal and interest premised on the assumed levy cannot stand. The blocked-credit restriction for goods or services used in construction of immovable property does not apply where no construction activity occurred. As the underlying transaction is not taxable and the blocked-credit premise fails, allegations of wrongful credit, fraud, wilful misstatement or suppression for section 74 proceedings, including consequential penalty, cannot be sustained. The adjudication and appellate demands were quashed, with refund of tax and interest directed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915