Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
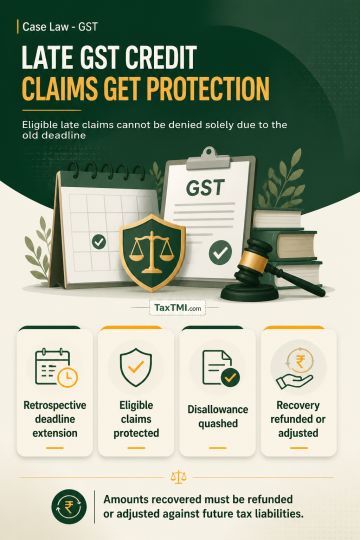
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921