Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
Page of 4915
Press 'Enter' after typing page number.
1421 to 1440 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
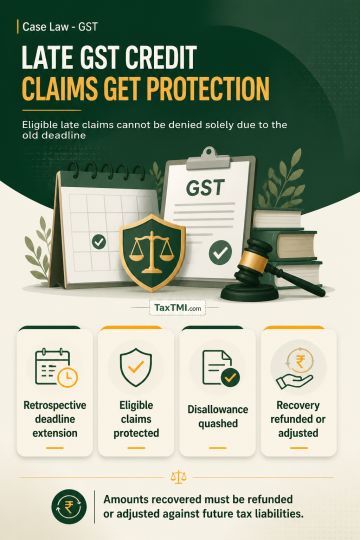
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915