Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
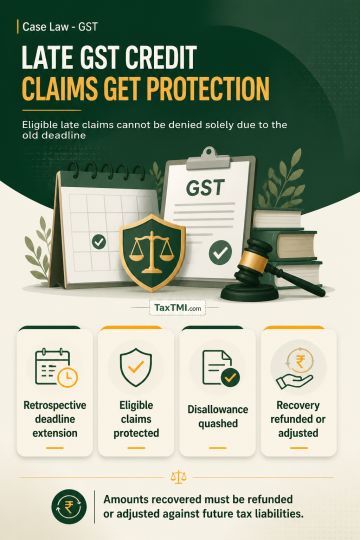
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918