Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
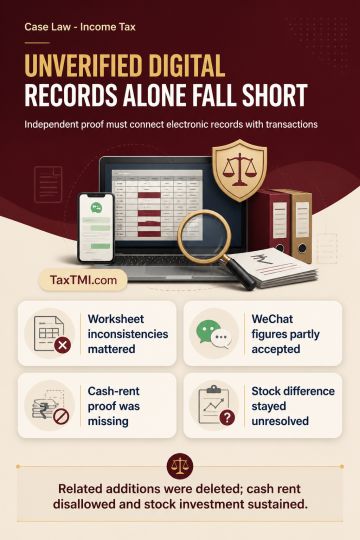
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915