Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
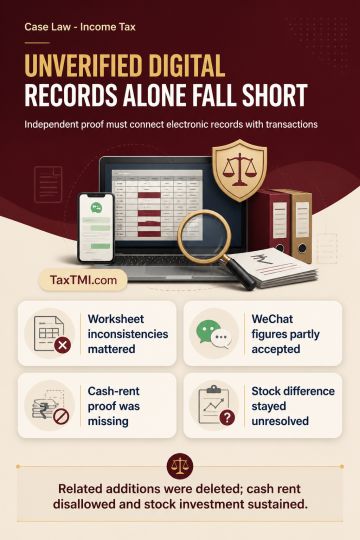
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI