Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
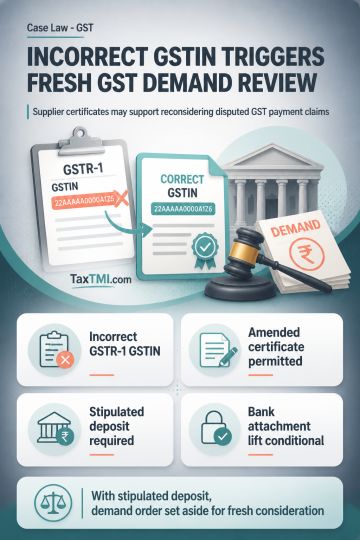
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915