Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Page of 4918
Press 'Enter' after typing page number.
1641 to 1660 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
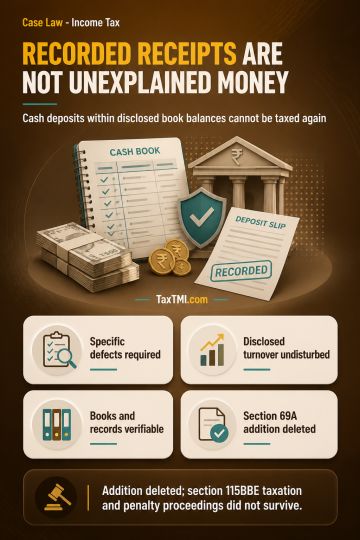
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918