Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Page of 4915
Press 'Enter' after typing page number.
1481 to 1500 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
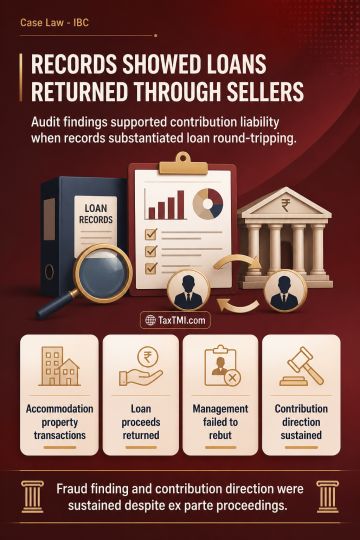
Forensic audit reports are not conclusive proof of fraud, but may support insolvency contribution liability when reliable documentary evidence substantiates their findings. Sale deeds, bank records, sub-registrar records and title-verification material supported findings that property transactions were accommodation arrangements used to raise loans. Loan proceeds substantially returned through sellers to the corporate debtor and related entities, establishing round-tripping intended to defraud creditors. Former management failed to rebut matters within its special knowledge. Ex parte determination remained valid because suspended directors received adequate opportunity to contest the proceedings and did not produce reliable contrary material. The fraudulent-transaction finding and consequential contribution direction were sustained.
Forensic audit reports are not conclusive proof of fraud, but may support insolvency contribution liability when reliable documentary evidence substantiates their findings. Sale deeds, bank records, sub-registrar records and title-verification material supported findings that property transactions were accommodation arrangements used to raise loans. Loan proceeds substantially returned through sellers to the corporate debtor and related entities, establishing round-tripping intended to defraud creditors. Former management failed to rebut matters within its special knowledge. Ex parte determination remained valid because suspended directors received adequate opportunity to contest the proceedings and did not produce reliable contrary material. The fraudulent-transaction finding and consequential contribution direction were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915