Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Page of 4916
Press 'Enter' after typing page number.
41 to 60 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
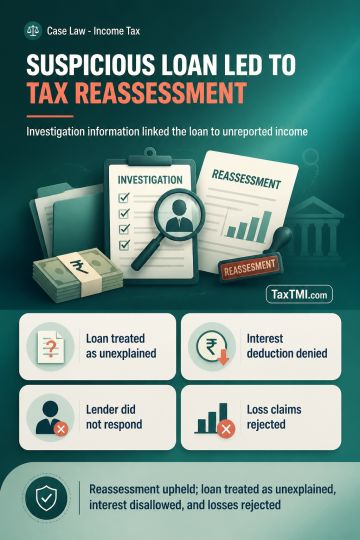
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916