Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
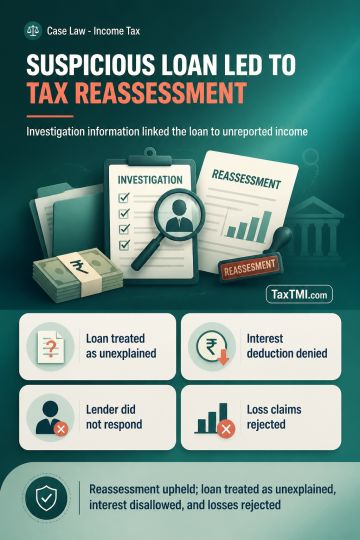
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918