Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Page of 4918
Press 'Enter' after typing page number.
81 to 100 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
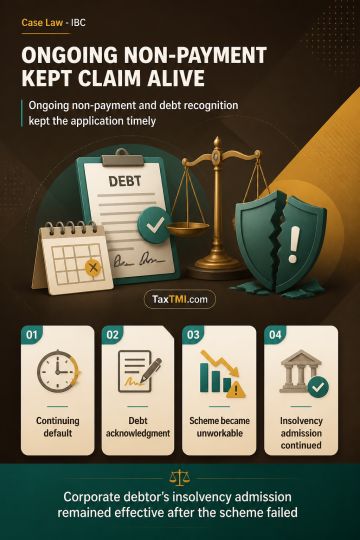
Continuing failure to deliver possession of an allotted unit or refund amounts received constituted a continuing default, creating a continuing cause of action for a financial creditor's insolvency application. Inclusion of the creditor's claim in a settlement scheme operated as an acknowledgment of debt, preventing the claim from being treated as time-barred. The application therefore remained within limitation. Once the revival scheme was declared unworkable and parties were permitted to revive insolvency proceedings, objections based on the scheme's subsistence and parallel proceedings no longer survived. The corporate debtor's admission into insolvency consequently remained effective.
Continuing failure to deliver possession of an allotted unit or refund amounts received constituted a continuing default, creating a continuing cause of action for a financial creditor's insolvency application. Inclusion of the creditor's claim in a settlement scheme operated as an acknowledgment of debt, preventing the claim from being treated as time-barred. The application therefore remained within limitation. Once the revival scheme was declared unworkable and parties were permitted to revive insolvency proceedings, objections based on the scheme's subsistence and parallel proceedings no longer survived. The corporate debtor's admission into insolvency consequently remained effective.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918