Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
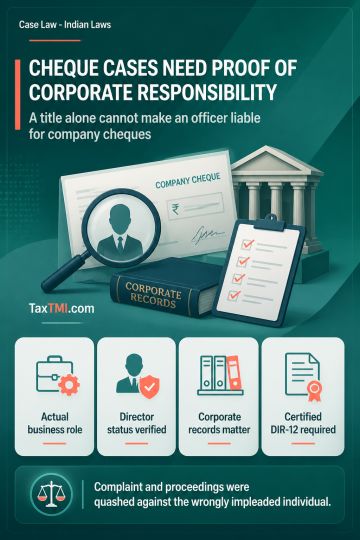
Vicarious liability under Section 141 of the Negotiable Instruments Act requires a person's actual role in and responsibility for the company's business when the cheque was dishonoured; a designation asserted in the complaint is insufficient. Uncontroverted Ministry of Corporate Affairs records showing that the impleaded individual was never a director, combined with no pleaded or disclosed role in company affairs, justified quashing the complaint and consequential proceedings against that individual as an abuse of process. For prospective cheque-dishonour complaints against companies, complainants must annex corporate identification details and certified Form DIR-12, unless unavailability despite due diligence is affirmed and the Magistrate records reasons before cognizance.
Vicarious liability under Section 141 of the Negotiable Instruments Act requires a person's actual role in and responsibility for the company's business when the cheque was dishonoured; a designation asserted in the complaint is insufficient. Uncontroverted Ministry of Corporate Affairs records showing that the impleaded individual was never a director, combined with no pleaded or disclosed role in company affairs, justified quashing the complaint and consequential proceedings against that individual as an abuse of process. For prospective cheque-dishonour complaints against companies, complainants must annex corporate identification details and certified Form DIR-12, unless unavailability despite due diligence is affirmed and the Magistrate records reasons before cognizance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918