Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
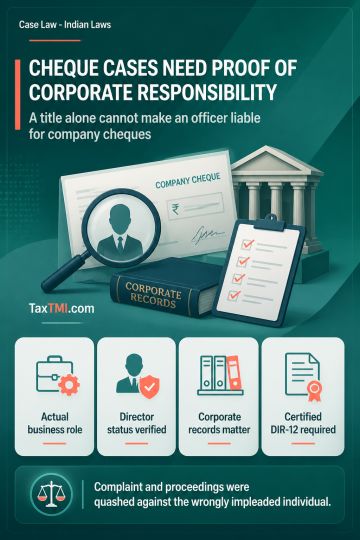
Vicarious liability under Section 141 of the Negotiable Instruments Act requires a person's actual role in and responsibility for the company's business when the cheque was dishonoured; a designation asserted in the complaint is insufficient. Uncontroverted Ministry of Corporate Affairs records showing that the impleaded individual was never a director, combined with no pleaded or disclosed role in company affairs, justified quashing the complaint and consequential proceedings against that individual as an abuse of process. For prospective cheque-dishonour complaints against companies, complainants must annex corporate identification details and certified Form DIR-12, unless unavailability despite due diligence is affirmed and the Magistrate records reasons before cognizance.
Vicarious liability under Section 141 of the Negotiable Instruments Act requires a person's actual role in and responsibility for the company's business when the cheque was dishonoured; a designation asserted in the complaint is insufficient. Uncontroverted Ministry of Corporate Affairs records showing that the impleaded individual was never a director, combined with no pleaded or disclosed role in company affairs, justified quashing the complaint and consequential proceedings against that individual as an abuse of process. For prospective cheque-dishonour complaints against companies, complainants must annex corporate identification details and certified Form DIR-12, unless unavailability despite due diligence is affirmed and the Magistrate records reasons before cognizance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918