Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
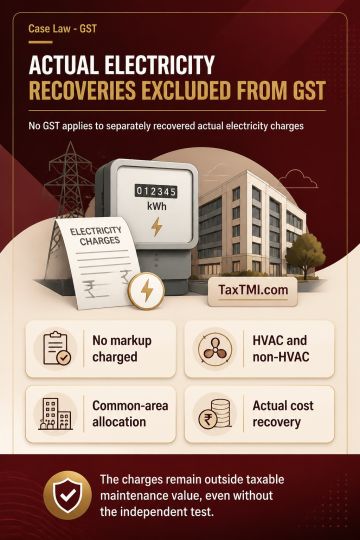
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI