Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
Under the 2017 Act, a single show-cause notice covering multiple...
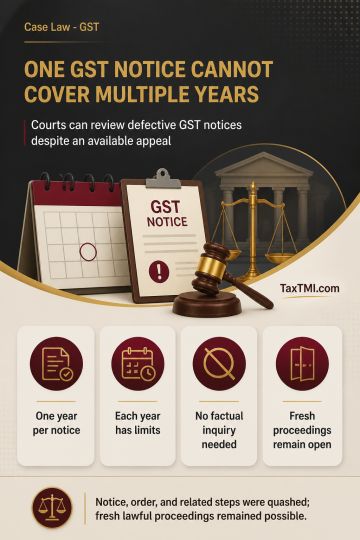
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate remedy.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Under the 2017 Act, a single show-cause notice covering multiple financial years is impermissible because limitation applies independently to each year and cannot be bypassed by clubbing years. Separate year-wise demands raised under such a notice do not cure the jurisdictional defect. A notice issued without or in excess of statutory jurisdiction may be challenged through writ jurisdiction despite an available appellate remedy where the defect is apparent on its face and requires no factual inquiry. The composite notice, consequential order-in-original and related steps were quashed, while revenue authorities remained free to initiate fresh proceedings in accordance with law.
Under the 2017 Act, a single show-cause notice covering multiple financial years is impermissible because limitation applies independently to each year and cannot be bypassed by clubbing years. Separate year-wise demands raised under such a notice do not cure the jurisdictional defect. A notice issued without or in excess of statutory jurisdiction may be challenged through writ jurisdiction despite an available appellate remedy where the defect is apparent on its face and requires no factual inquiry. The composite notice, consequential order-in-original and related steps were quashed, while revenue authorities remained free to initiate fresh proceedings in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI