Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
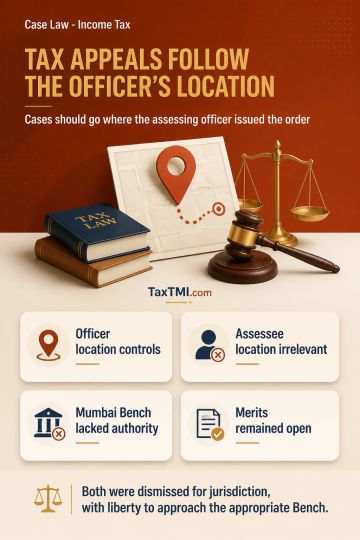
ITAT ordinary territorial jurisdiction is determined by the location of the Assessing Officer who issued the assessment order, rather than the assessee's location or that of the Commissioner (Appeals). The President's procedural rule-making power does not extend to transferring a pending appeal between Benches situated in different States. Where the assessment order originated from an Assessing Officer at Chennai, the Mumbai Bench lacked jurisdiction over both the Revenue's appeal and the assessee's related cross-objection. Both were dismissed for want of territorial jurisdiction, with liberty to approach the appropriate Bench; merits remained open.
ITAT ordinary territorial jurisdiction is determined by the location of the Assessing Officer who issued the assessment order, rather than the assessee's location or that of the Commissioner (Appeals). The President's procedural rule-making power does not extend to transferring a pending appeal between Benches situated in different States. Where the assessment order originated from an Assessing Officer at Chennai, the Mumbai Bench lacked jurisdiction over both the Revenue's appeal and the assessee's related cross-objection. Both were dismissed for want of territorial jurisdiction, with liberty to approach the appropriate Bench; merits remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920