Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
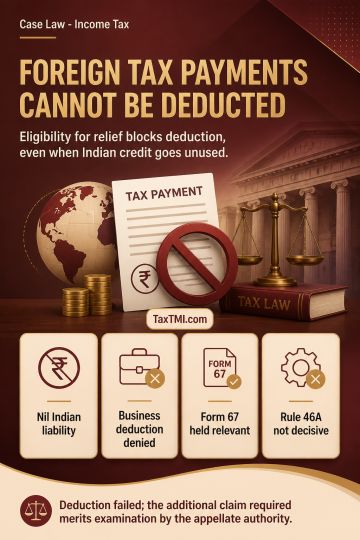
Foreign withholding tax eligible for double-taxation relief under sections 90 or 91 cannot be deducted as business expenditure merely because nil Indian tax liability prevents use of the credit. Explanation 1 to section 40(a)(ii) applies based on eligibility for relief, not actual allowance or utilisation; the claimed deduction was therefore rejected. An additional legal claim for that deduction, raised before the first appellate authority, required examination on merits where the return and Form 67 contained the relevant material. Rule 46A did not justify threshold rejection, although the claim ultimately failed.
Foreign withholding tax eligible for double-taxation relief under sections 90 or 91 cannot be deducted as business expenditure merely because nil Indian tax liability prevents use of the credit. Explanation 1 to section 40(a)(ii) applies based on eligibility for relief, not actual allowance or utilisation; the claimed deduction was therefore rejected. An additional legal claim for that deduction, raised before the first appellate authority, required examination on merits where the return and Form 67 contained the relevant material. Rule 46A did not justify threshold rejection, although the claim ultimately failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916