Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
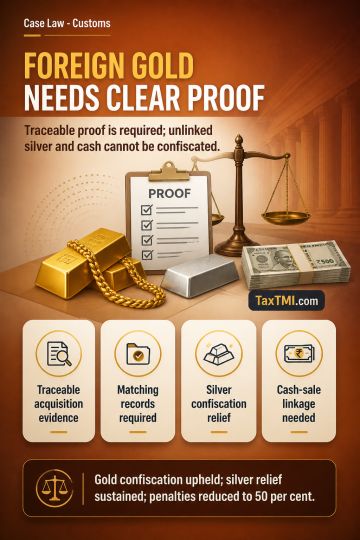
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923