Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Page of 4921
Press 'Enter' after typing page number.
1 to 20 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
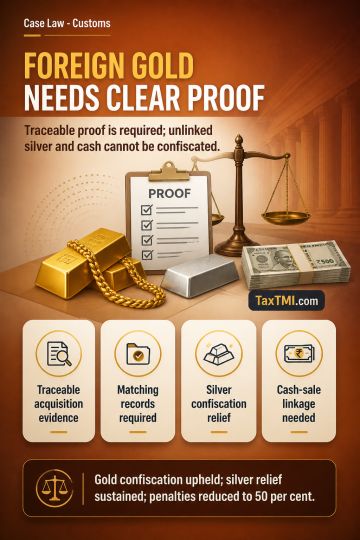
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI