Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
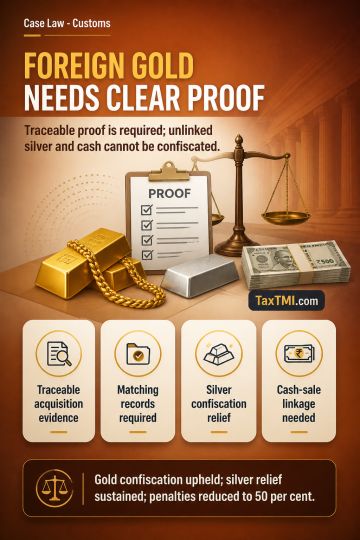
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
For foreign-marked gold, the reverse burden applies once the statutory conditions are met, requiring specific, credible and traceable evidence linking lawful acquisition to the seized articles. General business records and GST invoices that do not correspond to the seized gold, explain its foreign markings, or reconcile with relevant accounts do not discharge that burden; confiscation of the gold was therefore justified. For silver bullion, the burden does not shift without reasonable belief of smuggling, supported by a nexus beyond stock discrepancies; relief from confiscation was sustained. Cash may be confiscated as sale proceeds only on cogent evidence linking it to smuggled goods, not suspicion. Penalties were correspondingly reduced to 50 per cent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI