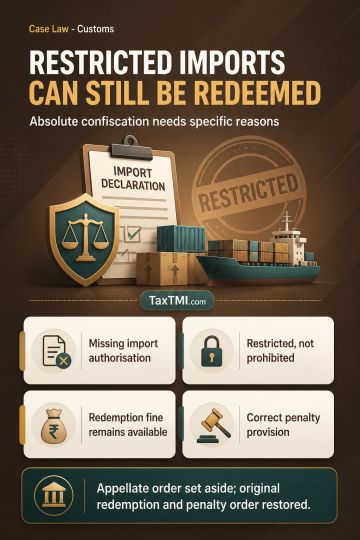
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
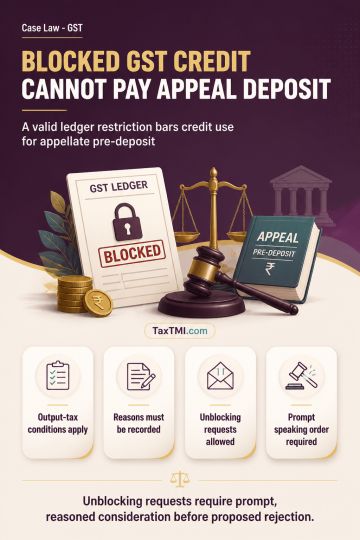
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916