Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
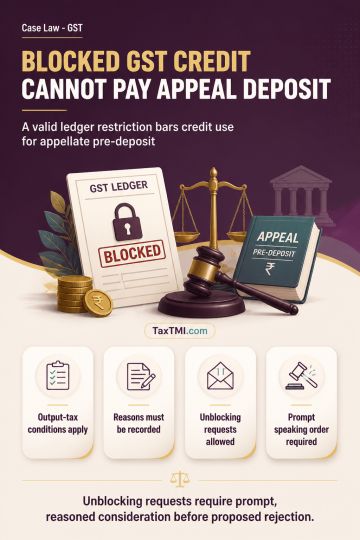
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI