Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
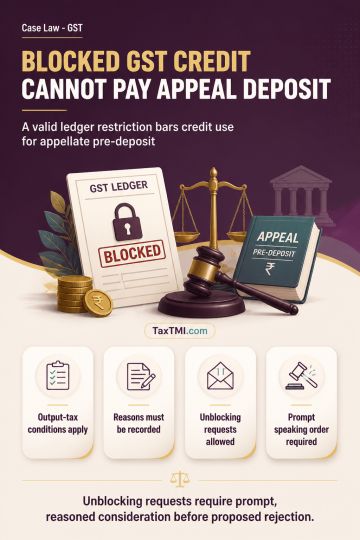
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918