Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
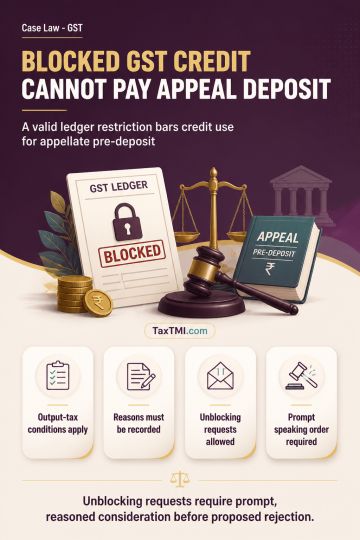
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Blocked input tax credit cannot be used for an appellate pre-deposit while a valid Rule 86A restriction prohibits debit of the electronic credit ledger. Section 49(4) permits use of ledger credit towards output-tax payments only subject to prescribed conditions and restrictions; it therefore creates no absolute right to use blocked credit for pre-deposit. Rule 86A operates provisionally, requires recorded reasons for the restriction, and permits an unblocking application when the grounds no longer subsist. The unblocking request must be considered expeditiously, with a speaking order and reasonable opportunity before any proposed rejection.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918