Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
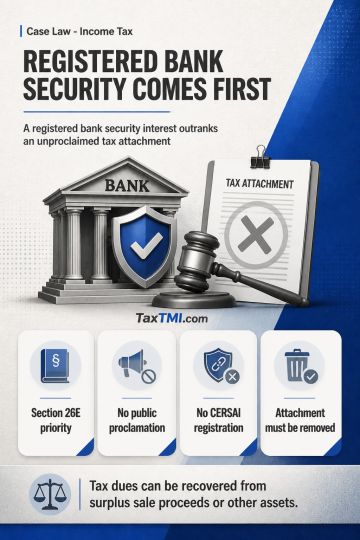
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Priority under section 26E of the Securitisation Act favours a bank's registered security interest over an Income Tax attachment where the Department has not publicly proclaimed the attachment in the prescribed manner or registered its claim or attachment order with CERSAI. A prior attachment alone does not displace the secured creditor's statutory priority. The attachment and resulting encumbrance must be removed to the extent they obstruct recovery of the bank's secured dues, while the Income Tax Department may recover its dues from surplus sale proceeds or other assets in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI