Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
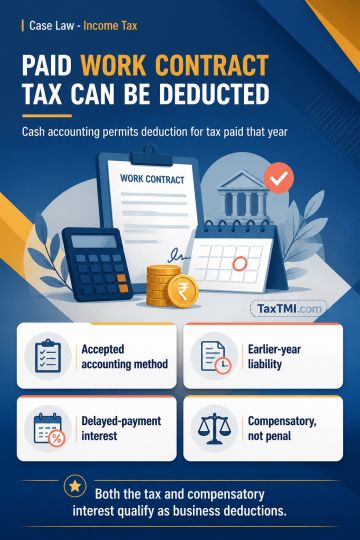
Work Contract Tax actually paid during the relevant previous year is deductible for an assessee consistently following the cash system of accounting, even where the statutory liability relates to earlier financial years. Once the books and accounting method are accepted, mercantile principles cannot be selectively applied to deny the deduction without material showing a mercantile method, manipulation, or accounting defects warranting intervention. Interest paid solely for delayed payment of Work Contract Tax is compensatory rather than penal in nature. As it compensates the State for delayed use of funds and relates to statutory business liability, the interest is allowable as a business deduction.
Work Contract Tax actually paid during the relevant previous year is deductible for an assessee consistently following the cash system of accounting, even where the statutory liability relates to earlier financial years. Once the books and accounting method are accepted, mercantile principles cannot be selectively applied to deny the deduction without material showing a mercantile method, manipulation, or accounting defects warranting intervention. Interest paid solely for delayed payment of Work Contract Tax is compensatory rather than penal in nature. As it compensates the State for delayed use of funds and relates to statutory business liability, the interest is allowable as a business deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI