Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
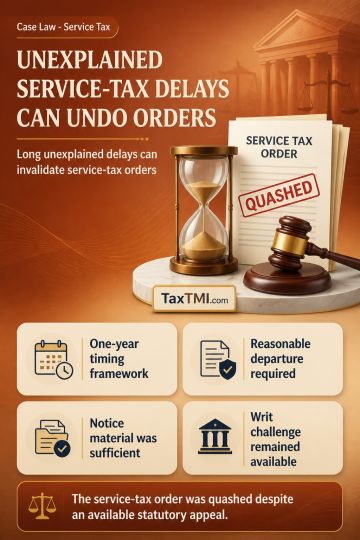
Section 73(4B)(b) requires service-tax adjudication, where possible, within one year when the extended period is invoked. The qualification permits only a reasonable and legally justifiable departure, not an unrestricted power to keep a show-cause notice pending for an inordinate period. Where the notice material enabled adjudication and no adequate explanation existed, representations or claimed adjournments could not justify prolonged delay. Unexplained delay rendered the adjudication arbitrary, contrary to Section 73(4B)(b) and Article 14, leading to quashing of the service-tax order. Availability of a statutory appeal did not bar writ jurisdiction because the challenge raised a legal question and involved arbitrary adjudication.
Section 73(4B)(b) requires service-tax adjudication, where possible, within one year when the extended period is invoked. The qualification permits only a reasonable and legally justifiable departure, not an unrestricted power to keep a show-cause notice pending for an inordinate period. Where the notice material enabled adjudication and no adequate explanation existed, representations or claimed adjournments could not justify prolonged delay. Unexplained delay rendered the adjudication arbitrary, contrary to Section 73(4B)(b) and Article 14, leading to quashing of the service-tax order. Availability of a statutory appeal did not bar writ jurisdiction because the challenge raised a legal question and involved arbitrary adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918